Looking for a Cash-Out Refinance in California? John Goodpaster specializes in helping homeowners access their home equity for debt consolidation, home improvements, or other financial goals. Let John guide you through the process to secure the best cash-out refinance terms available.
A Cash-Out Refinance allows you to refinance your existing mortgage for more than you currently owe and take the difference in cash. This option can be used for a variety of purposes, such as paying off high-interest debt, funding home improvements, or consolidating loans. A Cash-Out Refinance gives you the flexibility to access your home’s equity while potentially securing a better mortgage rate.
Homeowners who have built up equity in their property can benefit from a Cash-Out Refinance. Whether you need to pay off credit card debt, fund a large purchase, or make significant home improvements, this option gives you access to funds by leveraging your home’s equity. John Goodpaster helps California homeowners assess if a Cash-Out Refinance is the right option based on their financial situation and goals.
A Cash-Out Refinance involves replacing your current mortgage with a new, larger loan. The difference between the new loan amount and the current mortgage balance is given to you in cash. This option can help you secure a lower interest rate or access more favorable loan terms. While a Cash-Out Refinance can be used for a variety of financial needs, it’s important to understand the implications on your monthly payments. John Goodpaster will help you navigate the process and determine if this option is right for you.
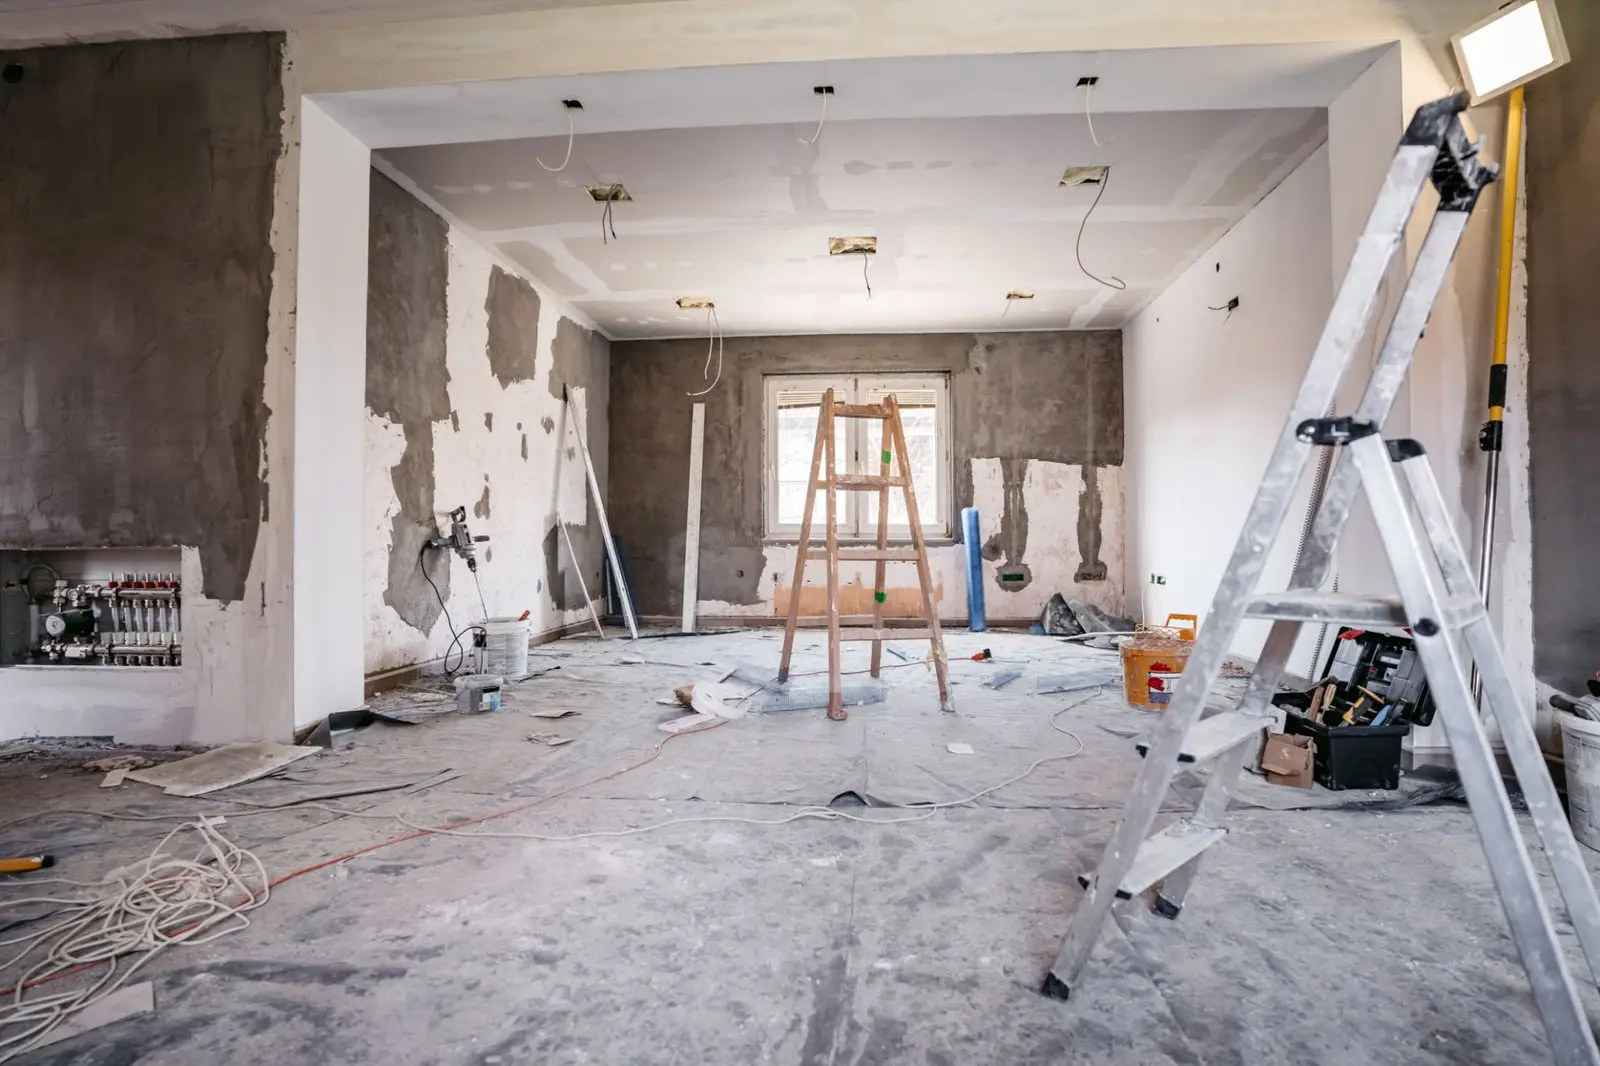
While a Cash-Out Refinance offers the advantage of accessing your home equity, it’s important to consider the potential risks. By increasing the size of your mortgage, you may face higher monthly payments or extend the time it takes to pay off your loan. Additionally, if property values decline, you could owe more than your home is worth. Understanding these risks is crucial before deciding to pursue a Cash-Out Refinance. John Goodpaster will help you assess whether the benefits outweigh the potential downsides based on your financial goals.
A Cash-Out Refinance may be a good option if you need funds for home renovations, debt consolidation, or other major financial goals. It’s also ideal for homeowners who have accumulated equity in their home and want to take advantage of today’s low-interest rates. However, it’s important to weigh the benefits against potential risks, as increasing your mortgage balance could affect your monthly payments. John Goodpaster will help you determine if this option is right for your financial goals and ensure you understand all the details before moving forward.
The main benefit of a Cash-Out Refinance is the ability to access the equity in your home to fund major expenses or consolidate debt. With a Cash-Out Refinance, you could potentially lock in a lower interest rate than your current mortgage, especially if rates have decreased since you first purchased your home. Additionally, you could use the funds for home improvements, which could increase the value of your property. John Goodpaster helps homeowners in California evaluate the financial benefits and ensure they secure the best terms for their Cash-Out Refinance.
With over 20 years of experience in the mortgage industry, John Goodpaster specializes in helping homeowners in California secure the best Cash-Out Refinance options. His deep understanding of the local real estate market and strong relationships with lenders ensure that you get competitive rates and the best terms available. John works with you to evaluate your financial situation, guide you through the application process, and help you make the most of your home’s equity.
Releasing equity affects the rate and repayment of the replacement loan. Review the whole transaction before committing the proceeds to a project or payoff.
Equity is value less debt, while cash-out proceeds are limited by the approved loan amount, required payoffs and costs. Lender and program limits restrict borrowing. Ask for a written calculation based on the proposed transaction rather than assuming all estimated equity is available.
A cash-out refinance replaces the first mortgage, so its new rate applies to the replaced balance as well as added borrowing. Compare that effect with keeping the first loan and adding eligible second-lien financing. The extra cash amount alone does not describe the cost.
Eligible proceeds may be used for permitted debt payoffs, but the resulting obligation is secured by the home. Compare total interest and payoff timing, not just monthly relief. Consolidation does not eliminate debt or prevent new balances from accumulating.
The lender assesses repayment ability, credit, liens and acceptable property value under the chosen program. Cash-out limits can differ by occupancy and loan type. An existing mortgage approval does not carry over automatically to the replacement loan.
No. The use of proceeds and applicable tax rules determine treatment. Ask a qualified tax adviser before budgeting around a deduction, especially for debt consolidation or spending unrelated to the home. Keep records tracing how the funds were used.
Confirm net proceeds, closing charges, the new balance, payment structure and expected completion conditions. Compare those figures with alternatives and your intended holding period. Do not schedule spending that depends on funds before the loan is actually completed and proceeds are available.
Information checked September 6, 2026. Sources: CFPB: Home equity borrowing · CFPB: No-closing-cost loans · VA: Cash-out refinancing · IRS: Mortgage interest deduction.