Renovation and Construction Loans are specialized mortgage products designed to help homeowners or buyers finance the construction or renovation of a property. These loans combine the cost of construction and long-term mortgage into a single loan. John Goodpaster helps guide clients through the process of securing these loans, ensuring they understand the details and options available to fund their building or renovation projects in California.
Renovation and Construction Loans are specialized mortgage products designed to help homeowners or buyers finance the construction or renovation of a property. These loans combine the cost of construction and long-term mortgage into a single loan. John Goodpaster helps guide clients through the process of securing these loans, ensuring they understand the details and options available to fund their building or renovation projects in California.
Renovation and Construction Loans are ideal for homeowners, real estate investors, and buyers looking to either build a new home or improve an existing one. Whether you’re purchasing a fixer-upper or constructing your dream home from scratch, these loans provide the financing needed to make your vision a reality. John Goodpaster works closely with clients in California to find the best loan options for their renovation or construction needs.
Renovation and Construction Loans allow borrowers to finance both the cost of construction and the long-term mortgage in a single loan. These loans typically allow you to only pay interest during the construction phase, with the loan converting to a traditional mortgage once the project is complete. John Goodpaster will help you understand the loan structures available, such as one-time and two-time close loans, ensuring you choose the best option for your project.
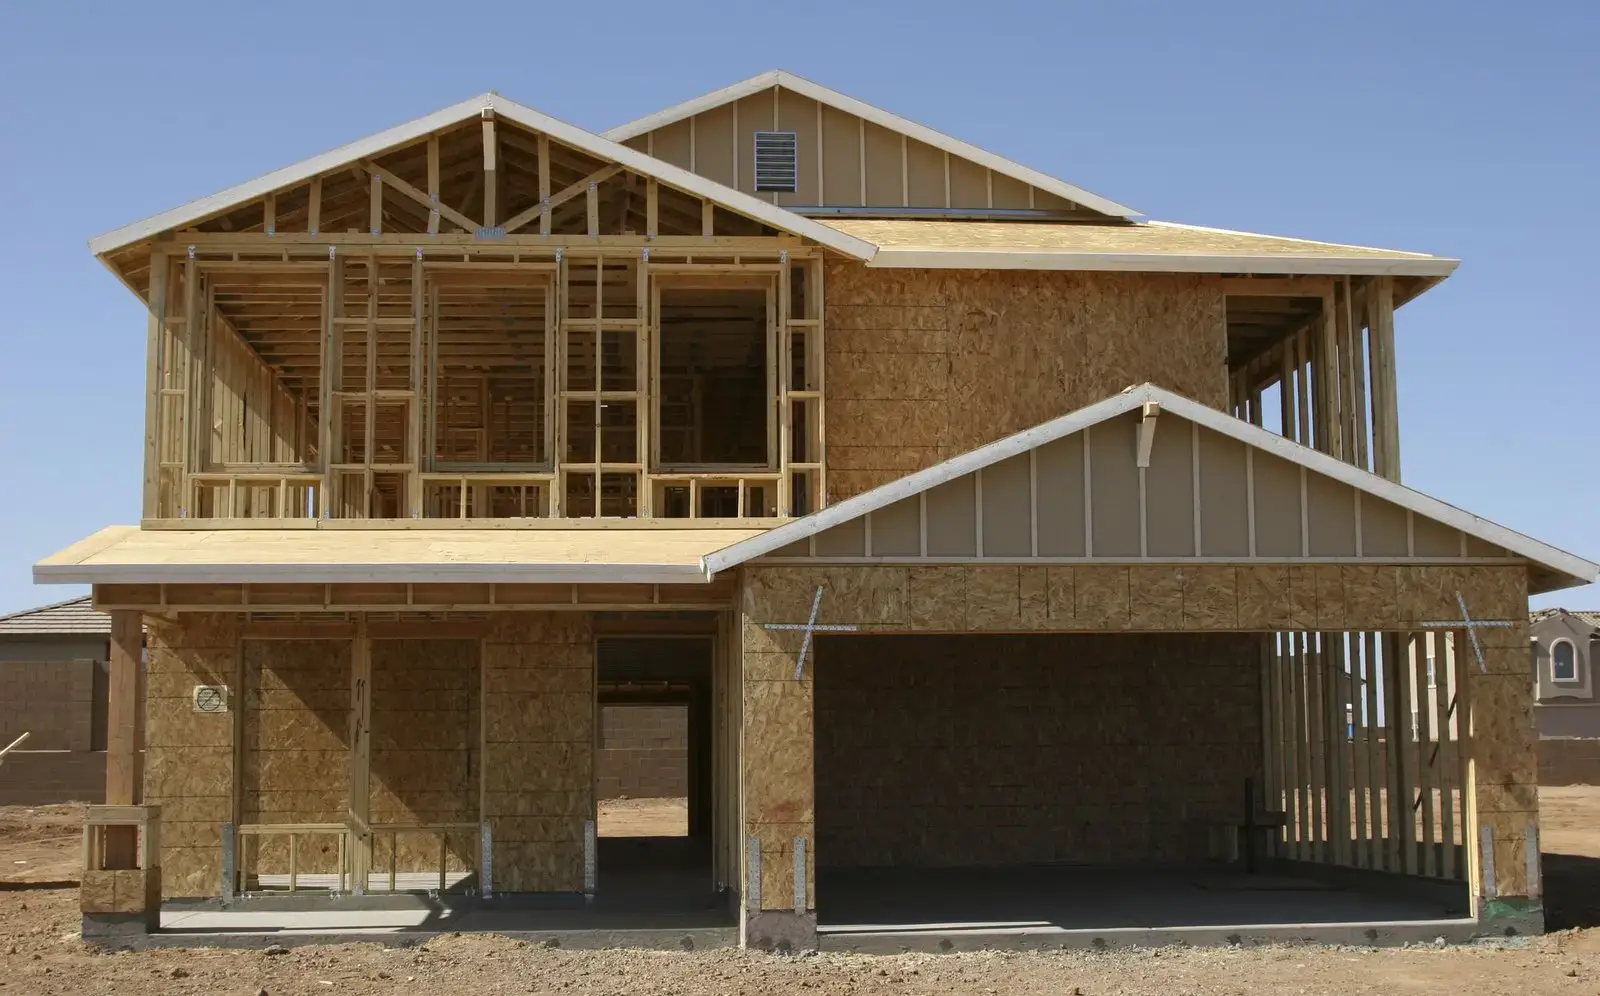
There are various types of Renovation and Construction Loans available, including FHA 203(k) Loans, Conventional Renovation Loans, and Construction-to-Permanent Loans. Each option has specific advantages depending on the property and the borrower’s situation. John Goodpaster can help you navigate these options and find the best loan for your renovation or construction project, whether you’re a first-time builder or an experienced investor.
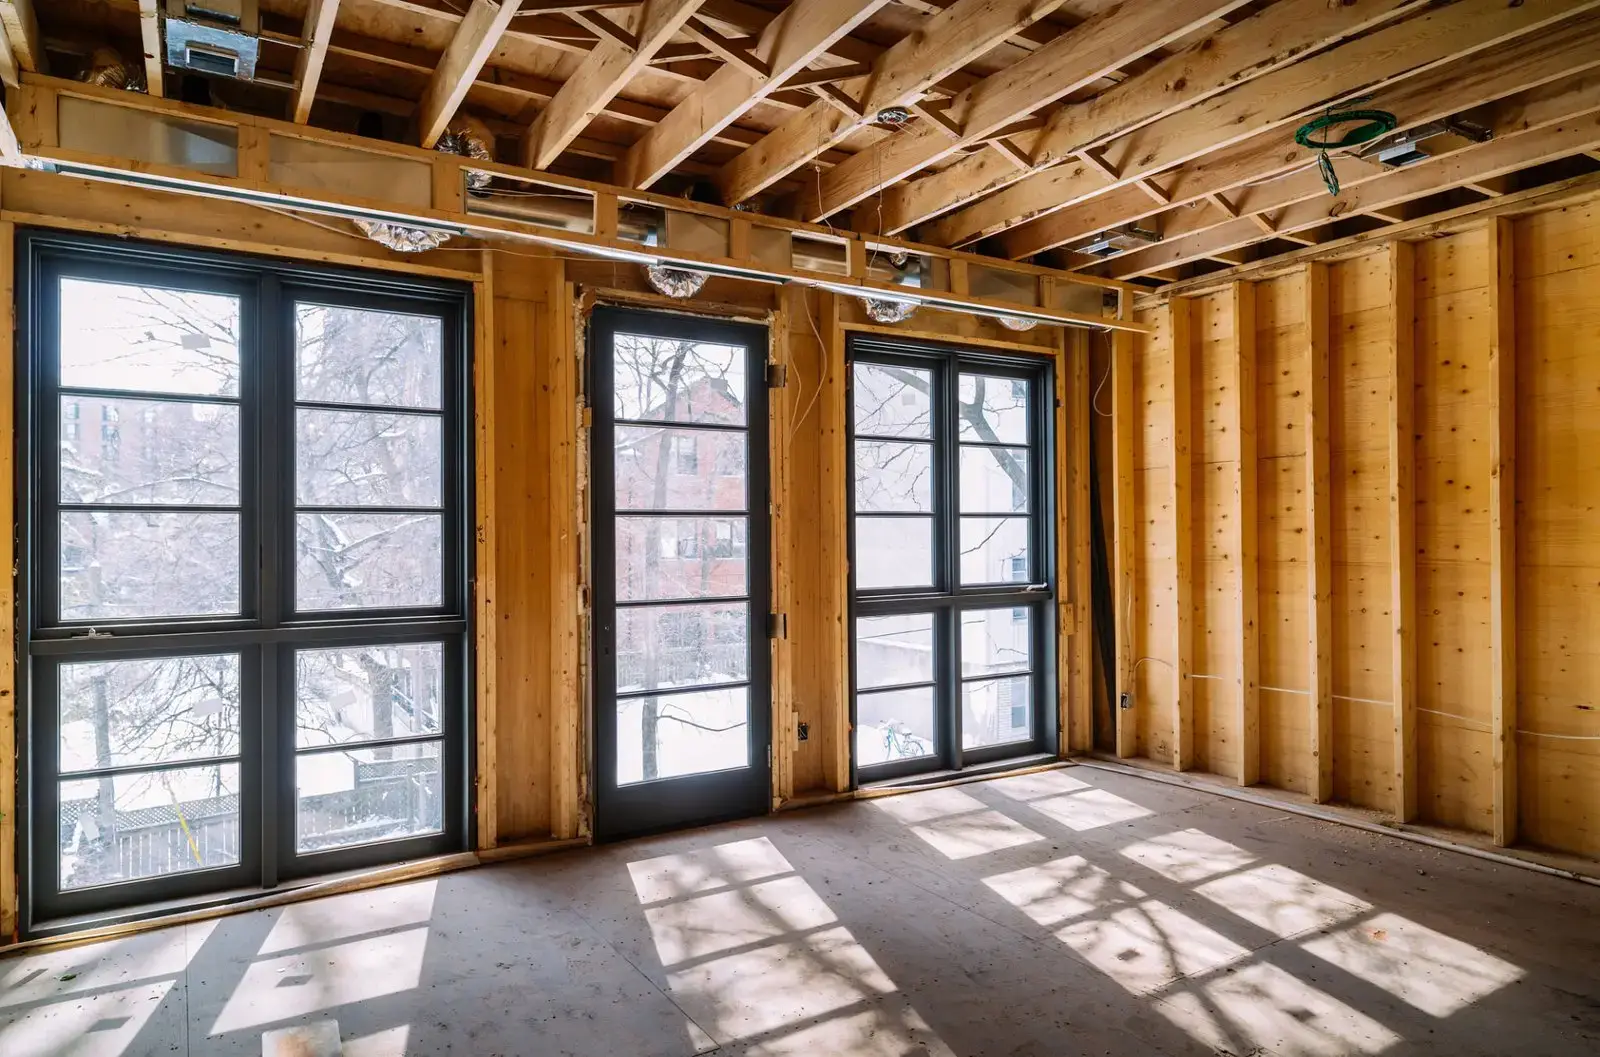
The primary benefit of Renovation and Construction Loans is that they provide a single loan to finance both the construction and the long-term mortgage. This saves time and money, as you avoid needing separate loans or refinancing. These loans also often come with competitive interest rates and flexible terms, making homebuilding or renovations more affordable. John Goodpaster helps clients take full advantage of these benefits, ensuring the loan process is simple and straightforward.
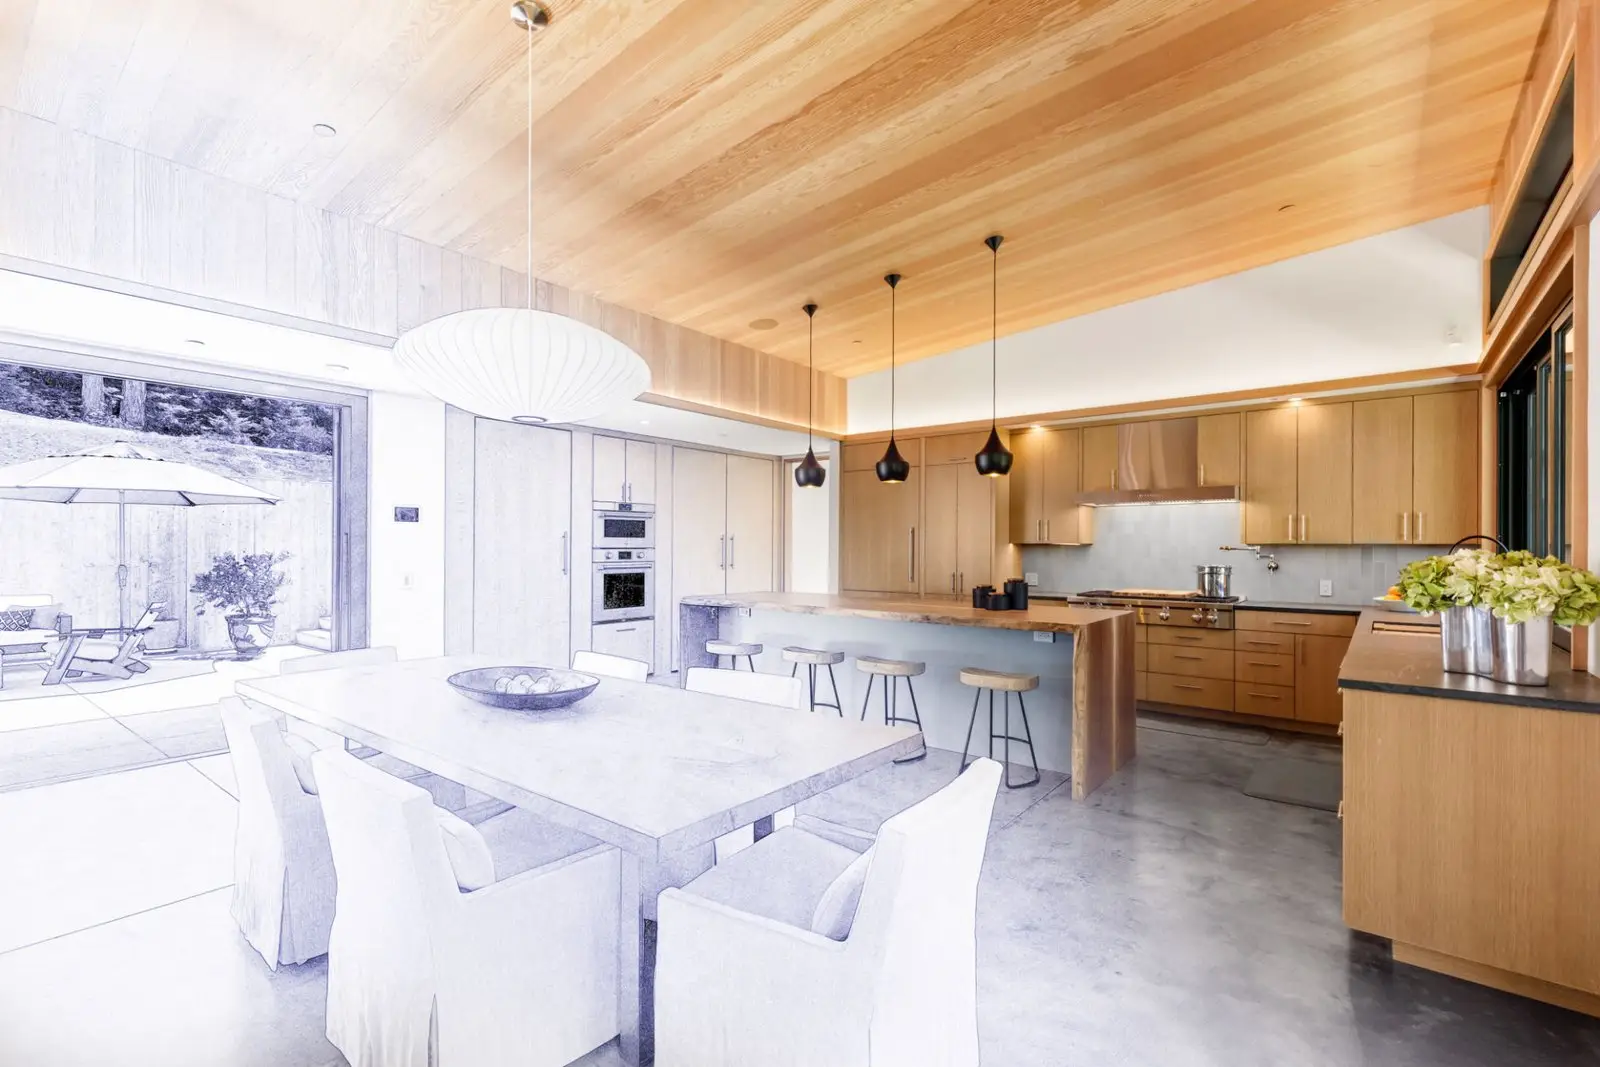
If you’re planning to build a new home or renovate an existing property in California, a Renovation or Construction Loan could be a great option. These loans are perfect for individuals or investors who need financing for both the construction and long-term mortgage. John Goodpaster will guide you through the process, help you understand the different loan options, and ensure you get the best terms for your project.
With over 20 years of experience in the mortgage industry, John Goodpaster specializes in helping homeowners and real estate investors in California secure the best Renovation and Construction Loans. His expertise in navigating these specialized loan options ensures you get the best terms and a streamlined process. John works closely with you from start to finish, making the process as simple and stress-free as possible, and ensuring your building or renovation project is funded efficiently.
Before committing to a fixer-upper or building project, check that the loan, contractor schedule and property requirements work together.
Discuss the proposed work early. A lender must confirm that the property condition, project scope and program fit; an ordinary purchase loan may not accept major unfinished repairs. A renovation approval also depends on your finances and the required contractor documentation.
A renovation program funds eligible work on an existing home, often alongside its purchase or refinance. A construction loan supports a new build and may have separate permanent financing. Ask which stages require approval, valuation and closing costs under the proposed structure.
The bid helps establish eligible costs, feasibility and the payment schedule. Plans, permits, contractor approval and completion requirements may also be needed. A seller’s renovation estimate does not necessarily meet underwriting requirements or account for everything the project will cost.
Many programs hold funds for staged disbursement following inspections or other verification. Confirm who requests and authorizes a draw and when the contractor can expect payment. Do not promise an advance the loan’s disbursement rules will not permit.
Include a suitable contingency and any overlapping housing expense in the budget. Ask what happens if deadlines change or the finished value differs from expectations. Extra borrowing and loan extensions require approval; neither should be treated as automatic.
For eligible improvements, compare renovation financing with a HELOC, a home equity loan and cash-out refinancing where available. Consider the effect on the current first mortgage, rate changes and total repayment. The project size and timing influence which structure is practical.
Information checked September 6, 2026. Sources: CFPB: Construction loans · HUD: FHA 203(k) program · Fannie Mae: HomeStyle Renovation · CFPB: Construction loan disclosures.